Lottery Tax Calculator (October 2026)
What a jackpot actually pays, after the 24% the lottery holds back, the rest of the federal bill that lands at filing, and whatever your state takes.
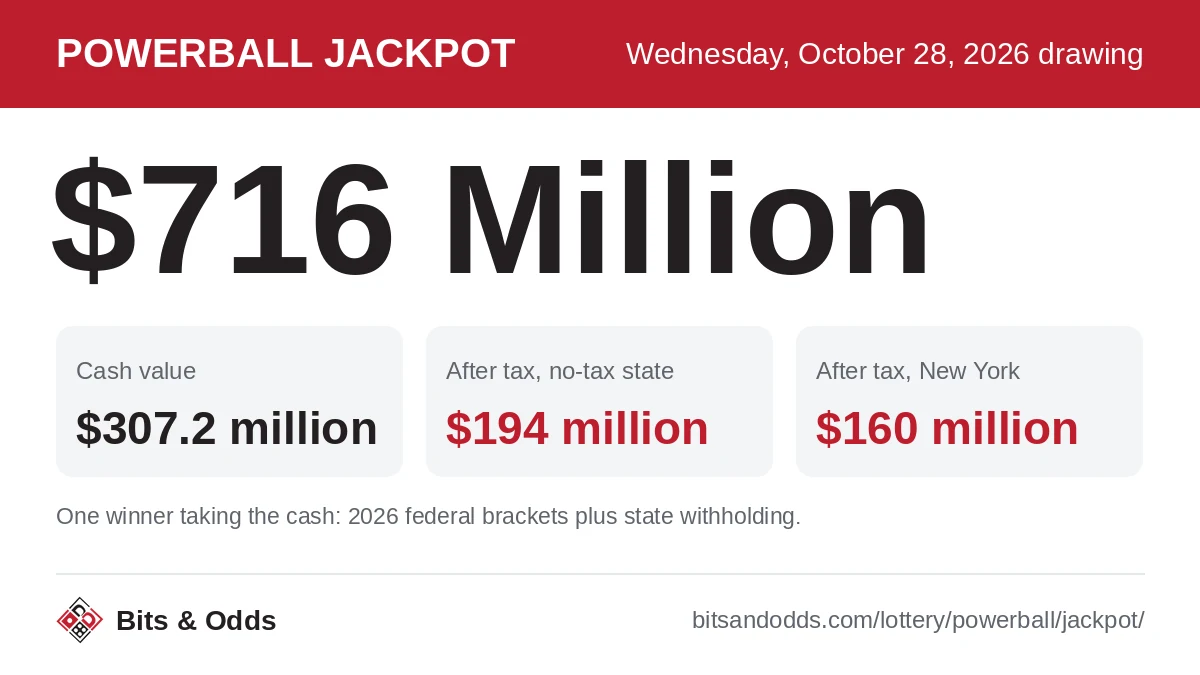
The Powerball jackpot for the October 28, 2026 draw is $716 million, with a cash value of $307.2 million. A single winner who takes the cash keeps about $194 million once the whole federal bill is paid, in a state that does not tax lottery prizes, and about $160 million in New York (10.90%). Every state that sells Powerball, or change the figures below.
What you would take home
An estimate, not tax advice. Federal figures use the statutory 2026 brackets and the standard deduction; state figures are withholding rates, which is what is held back at payout rather than what you finally owe — a state can withhold less than its top rate and bill the rest later. State rates were last checked on October 18, 2026 and do change. Nobody should make a decision about a life-changing sum from a web page: talk to a tax professional before you claim.
Why the 24% figure misleads
Every article about lottery tax leads with 24%, because that is what the lottery withholds before it writes the cheque. It is not the bill. Federal income tax is graduated, and a jackpot lands almost entirely in the top bracket — 37% in 2026. So a winner who plans around 24% is short by roughly thirteen percentage points of the whole prize, due the following April. On a $500 million cash option that gap is over $30 million.
Lump sum against annuity
The advertised jackpot is what the annuity pays over 30 years, in payments that each grow 5% on the one before. The cash option is the prize pool itself — about 43% of the advertised figure — paid now. The calculator shows both after tax, which is the only fair way to compare them: the annuity spreads income across thirty tax years, so a slice of each payment is taxed in the lower brackets rather than all of it at the top rate.
That is a genuine advantage for the annuity and it is smaller than it looks, because most of each payment still lands in the top bracket. What it cannot tell you is what you would have earned by investing the lump sum instead, which is the actual question — and one we are not qualified to answer.
The states that take nothing
14 jurisdictions withhold nothing on lottery prizes: Alabama, Alaska, California, Delaware, Florida, Hawaii, Nevada, New Hampshire, South Dakota, Tennessee, Texas, Utah, Washington, Wyoming. Most have no income tax at all. California is the exception worth knowing — it taxes income normally but exempts California Lottery prizes by statute. Delaware is different: it withholds nothing at payout, but the Delaware Lottery says its prizes are subject to Delaware income tax, so you settle it when you file. At the other end, New York (10.90%), District of Columbia (10.75%), Maryland (9.50%). On a large jackpot that spread is worth tens of millions.
Lottery taxes by state
Each state's page has its withholding rate and where it is published, the prize it starts at, three worked prizes and what the current Powerball jackpot leaves a winner there.
Powerball $716 million after taxes, by state
What a single winner of the October 28, 2026 Powerball jackpot keeps after taking the $307.2 million cash, in each state. Each page has the lump sum against the annuity, the federal bill against what is withheld, and the state's tax.
Mega Millions $463 million after taxes, by state
What a single winner of the October 30, 2026 Mega Millions jackpot keeps after taking the $194.9 million cash, in each state. Each page has the lump sum against the annuity, the federal bill against what is withheld, and the state's tax.
Check your numbers first
Frequently asked questions
- How much tax do you pay on lottery winnings?
- The lottery withholds 24% for federal tax before it pays you, but that is not your bill — it is a down payment. A jackpot puts you in the 37% federal bracket, so you owe the difference at filing. On top of that your state may withhold up to 10.90%. The calculator above does both.
- Why is the 24% withholding not the final answer?
- Withholding is a flat rate applied at payout; your actual liability is worked out on your whole year's income at graduated rates. Because a jackpot lands almost entirely in the top bracket, nearly every large winner owes a further 13 percentage points at filing. Winners who spend as if 24% was the bill are the classic way this goes wrong.
- Which states do not tax lottery winnings?
- 14 withhold nothing: Alabama, Alaska, California, Delaware, Florida, Hawaii, Nevada, New Hampshire, South Dakota, Tennessee, Texas, Utah, Washington, Wyoming. Most simply have no income tax. California is the interesting one — it taxes income but exempts California Lottery prizes. Delaware withholds nothing when it pays out, but its prizes are still taxable income when you file.
- Is the lump sum or the annuity better?
- The annuity pays more in total — the advertised jackpot, in 30 payments each 5% larger than the last. The lump sum is roughly 43% of that, now. Which is better depends on what you would earn on the money and on tax rates over three decades, so it is a question for an accountant rather than a website. The calculator shows both so you can see the actual gap.
- Do I pay tax where I bought the ticket or where I live?
- Usually both are involved: the state where the ticket was sold withholds first, and your home state taxes the income and generally credits what the other state took. Several states also apply a higher rate to non-residents. If you have crossed a state line to buy, that is a question for a tax professional, not this page.